






Overview
- The Federal Reserve raised the federal funds target range by 25 basis points to 3.75%–4.00% on 16 September, with all 12 voting members supporting the decision.
- Fed projections still point to further tightening. The median end-2026 federal funds rate projection stands at 4.1%, while 16 of 18 participants projected a year-end rate above the current midpoint.
- Energy remains a major inflation risk as Middle East oil supply risks stays in focus.
- Traders now shift their attention to US flash PMIs, initial jobless claims, the SNB rate decision and durable goods orders for signals on growth and labour demand.
September changes the interest rate path
On 16 September, the Federal Open Market Committee raised its target range by 25 basis points to 3.75%–4.00%. The 12-0 vote marked the first US rate increase in more than three years and following a period of renewed inflation pressure and higher energy costs.
The September Summary of Economic Projections showed a median federal funds rate of 4.1% at the end of 2026. Of the 18 participants, 16 placed their year-end projection at 4.125% or 4.375%, reflecting the consensus for an additional raise from the current midpoint of 3.875%.
This suggests a cautious approach to monetary policy, with expectations for rate hikes in 2026 and a potential easing in 2027. For traders, understanding how to trade interest rate expectations can help put changes in Fed outlook into a broader market context.
Another increase remains possible if inflation stays firm while growth and employment continue to absorb tighter financial conditions.
Energy remains tied to the inflation outlook
Oil continues to complicate the policy picture. The conflict in the Middle East has kept crude oil prices elevated, disrupting normal supply routes.
High energy costs can feed into transport, manufacturing and consumer prices. This keeps inflation expectations high even when other price pressures begin to cool. This relationship places crude oil alongside PCE inflation and labour data as important pieces to consider for the next Fed decision.
The White House and Fed remain on different policy paths
US monetary policy also experiences conflict as the White House and Central Bank are facing different policy expectations.
President Donald Trump has continued to argue for US interest rates of 1% or lower. The Fed, by contrast, raised rates in September as it focused on inflation returning towards its 2% target.
Economic conditions likely forced Warsh toward a decision that conflicted with the White House’s preference. Persistent inflation, resilient economic activity and rising concern in the bond market remain a big concern. Before the meeting, markets had already moved strongly toward expecting a hike and analysts warned that failing to act could itself undermine confidence in the Fed’s commitment to price stability.
Markets are now trading the second-order effects
The US dollar strengthened after the decision. By Monday, the Dollar Index was around 100.23. US two-year Treasury yields had also climbed to 4.76% as traders adjusted to a tighter policy outlook.
Changes in Treasury yields can transmit quickly across currencies and precious metals. The relationship between US Treasury yields and gold therefore remains an important part of the post-Fed market picture.
Gold initially fell after the rate increase but recovered as oil prices and the dollar eased. Spot gold reached $4,390.11 on Friday and recorded its first weekly rise in four weeks.
US equities had a more mixed week. The S&P 500 ended Friday at 7,650.50, down 0.1% for the week. The Nasdaq gained 0.7%, while the Dow fell 1.7%.
Growth data back in focus
The next major US inflation release is not due until 30 September, when the Bureau of Economic Analysis publishes August Personal Income and Outlays, including the PCE price indexes. The report plays an important role as it reflects changes in the prices of goods and services purchased by consumers and is the Federal Reserve’s preferred measure of inflation.
US flash manufacturing PMI is forecasted at 53.4, down from 53.9, while flash services PMI is forecasted at 56.0 after 56.5 previously. Initial jobless claims are forecast at 201,000 after falling to 196,000 in the previous week. A continued reading near 200,000 would keep the labour market consistent with the Fed’s description of employment data.
Key Symbols to Watch
USDX | EURUSD | GBPUSD | USDJPY | GOLD
Upcoming Events
| Date | Currency | Event | Forecast | Previous | Analyst Remarks |
| 23 Sep 2026 | USD | Flash Manufacturing PMI | 53.4 | 53.9 | A reading above 50 would keep manufacturing in expansion. An upside surprise could support US yields and the dollar. |
| 23 Sep 2026 | USD | Flash Services PMI | 56 | 56.5 | Services remain the stronger part of the US economy. Stable activity could reinforce expectations for tighter Fed policy. |
| 24 Sep 2026 | CHF | SNB Policy Rate | 0.00% | 0.00% | A hold is widely expected. Guidance on inflation and the Swiss franc could drive CHF volatility. |
| 24 Sep 2026 | USD | Unemployment Claims | 201K | 196K | Another firm result could reinforce the idea that labour markets can absorb tighter policy. |
| 25 Sep 2026 | USD | Durable Goods Orders m/m | -0.30% | 1.10% | A stronger reading could support growth expectations and Treasury yields. |
For a full view of upcoming economic events, check out VT Markets’ Economic Calendar.
Key Movements of the Week
USDX
- USDX tested the 100.00 area for the second time and price traded down. However more price action is needed.
- Should price move lower, monitor price action at 99.40.
- In the event price consolidate at 100.00 and trade higher next, look for bearish price action above 100.31 or at 100.80 area
EURUSD
- EURUSD is still trading at the 1.1490 monitored area.
- Should price move up from current area, monitor price action at 1.1530. Any consolidation would mean EURUSD could trade higher.
- In the event EURUSD trade lower, look for bullish price action at 1.1390
GBPUSD
- GBPUSD traded up from the 1.3350 monitored area, but more price action is needed.
- Should GBPUSD trade lower, look for bullish price action at 1.3290
USDJPY
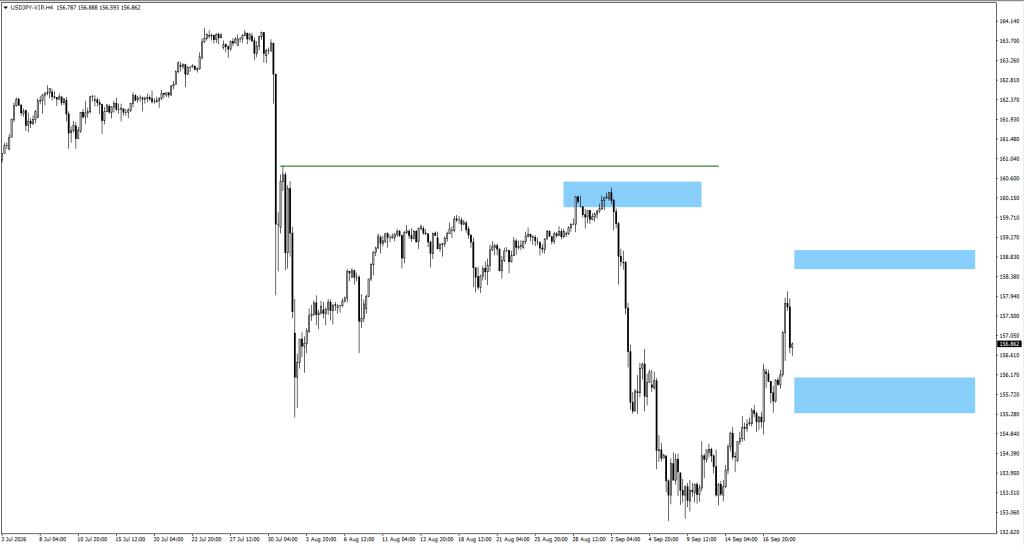
- More bearish momentum was needed for the price to go lower from 156.00.
- If USDJPY trades lower, look for bullish price action at 155.85.
- Should the price trade higher, look for bearish price action at 158.75.
GOLD
- As Gold moves up, monitor price action once price breaks 4403, 4434 or 4510.
- Should price break above 4510, look for bearish price action at 4600.
Bottom Line
The Fed has shifted the market from debating whether tightening would return to assessing how far the new cycle could extend. The 3.75%–4.00% policy range, a 4.1% median year-end rate projection and persistent energy pressure keep the US dollar and Treasury yields supported by tighter policy expectations. At the same time, gold, equities and Bitcoin have shown that the reaction is unlikely to move in one direction. This week’s flash PMIs, jobless claims, SNB decision and durable goods data will help traders judge whether growth remains strong enough for the Fed to tighten again. The next major US inflation test follows on 30 September with the August PCE release.
Create a live VT Markets account today to access our platform features, including market insights and educational content.
FAQ
Why did the Federal Reserve raise interest rates in September 2026?
The Federal Reserve raised the federal funds target range by 25 basis points to 3.75%–4.00% as inflation remained above target and economic activity stayed firm. Policymakers also kept the door open to further tightening if price pressures remain persistent.
Could the Fed raise rates again in 2026?
Yes. The Fed’s September projections suggest that further tightening remains possible before year-end. Upcoming inflation, labour market and growth data will play a key role in shaping the next decision.
How could higher interest rates affect the US dollar?
Higher US interest rates can support the dollar by increasing the relative appeal of dollar-denominated assets.
What are the main risks for US equities?
Higher Treasury yields remain a headwind for rate-sensitive sectors, while strong growth data could reinforce expectations for further Fed tightening.
Which economic events should traders watch this week?
Key events include US flash manufacturing and services PMIs, initial jobless claims, the SNB policy decision and US durable goods orders. These releases may influence expectations for growth, inflation and future central bank policy.
Start trading now — click here to create your real VT Markets account.



