





Key Points
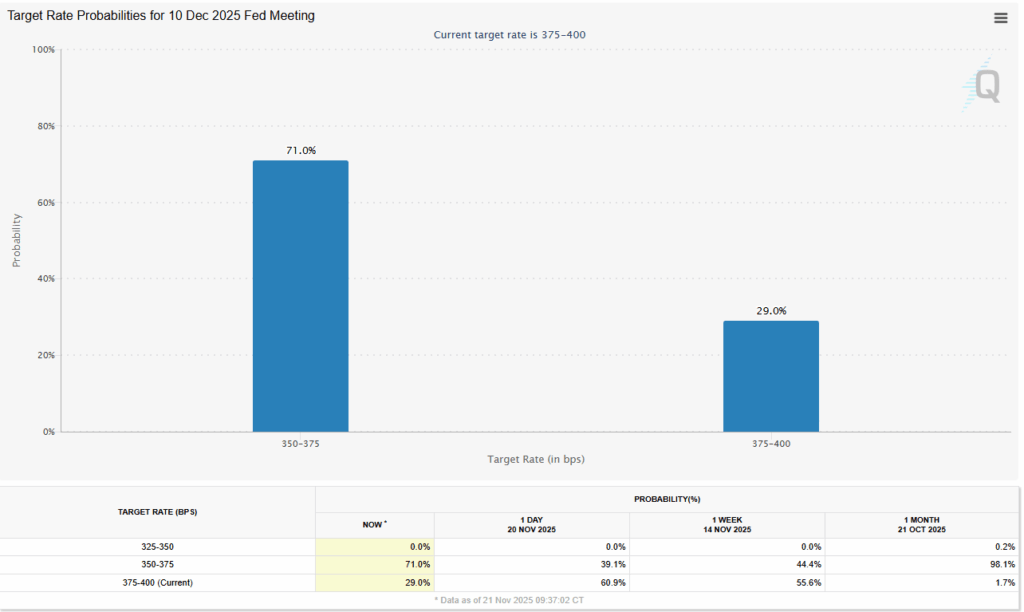
- Traders eye the 10 December FOMC meeting for confirmation of a potential 25 bps rate cut.
- USD weakens as FedWatch shows a 71% chance of easing.
- Risk assets rise, with gold bouncing from $4,020 support.
After months of “higher for longer” rhetoric, the latest labour data revealed a cooling but resilient jobs market. The delayed September NFP showed 119,000 jobs added, double expectations, but the jobless rate rose to 4.4%: the highest in four years. Revisions to July and August figures pointed to a slower trend overall.
The mixed tone leaves the Fed navigating a narrow path: strong hiring in key sectors like healthcare and education contrasts with rising continuing claims.
This divergence underpins the growing belief that inflation is cooling faster than employment.
Traders Price in a December Cut
FedWatch probabilities flipped sharply last week. Markets now assign a 71% chance of a 25 bp cut at the 10 December FOMC, compared with just 39% a day earlier. For January 2026, traders see a 58% likelihood of another 25 bp cut, highlighting growing conviction that easing will begin soon.
Lower yields boosted equities and weighed on the dollar. The 2-year Treasury yield slipped toward 3.5%, while AI and tech names led the rally. Bitcoin and Ethereum’s selloff has weakened, aligning with the broader mild “risk-on” rotation driven by softer yields and rising expectations of a December rate cut.
Risk Appetite Returns
The S&P 500 rebounded after two weeks of losses, supported by dovish expectations and strong corporate earnings. Over 80% of S&P 500 firms beat profit forecasts, driven by tech and healthcare sectors.
Meanwhile, oil prices stabilised after rebounding from the $57.60 support zone, and gold held firm near $4,000, supported by a softer USD.
Key Symbols to Watch
- XAUUSD
- USDX
- SP500
- BTCUSD
- USOil
Upcoming Events
| Date | Currency | Event | Forecast | Previous | Analyst Remarks |
| 25 Nov | USD | PPI m/m | -0.10% | -0.10% | Soft data could weigh on USD sentiment |
| 26 Nov | NZD | Official Cash Rate | 2.25% | 2.50% | RBNZ expected to maintain cautious tone |
| 26 Nov | USD | Core PCE Price Index m/m | 0.20% | 0.20% | Inflation gauge to steer FOMC expectations |
| 26 Nov | USD | Prelim GDP q/q | 2.50% | 2.90% | Focus on growth momentum before FOMC |
| 28 Nov | CAD | GDP m/m | 0.20% | -0.30% | Growth rebound may strengthen CAD ahead of December data |
Key Movements of the Week
Gold (XAUUSD)
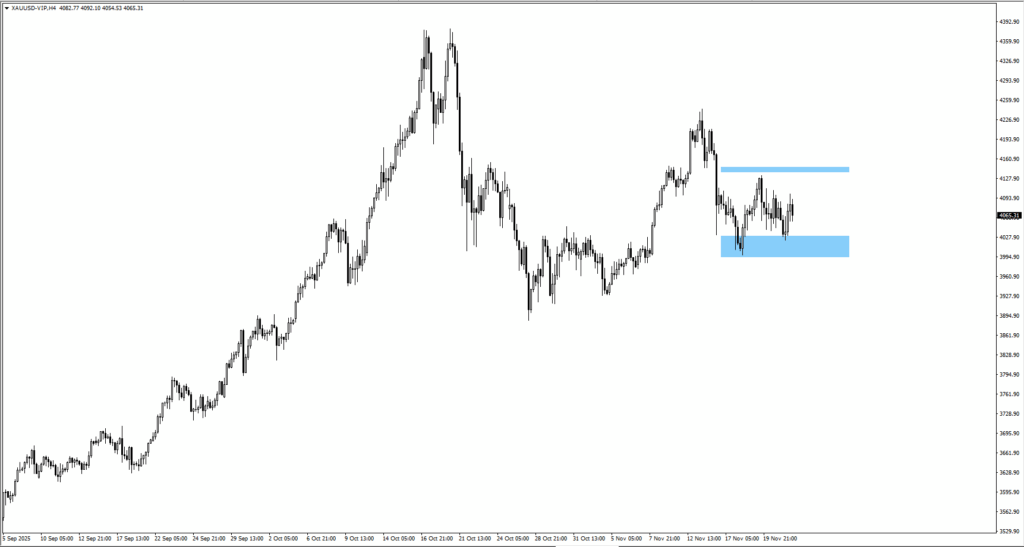
- Gold bounced from $4,020, continuing its range between $3,940 and $4,075.
- Softer yields and rising cut odds underpin support near $4,000.
- A break below $3,940 could expose $3,900, while resistance remains at $4,075.
S&P 500 (SP500)
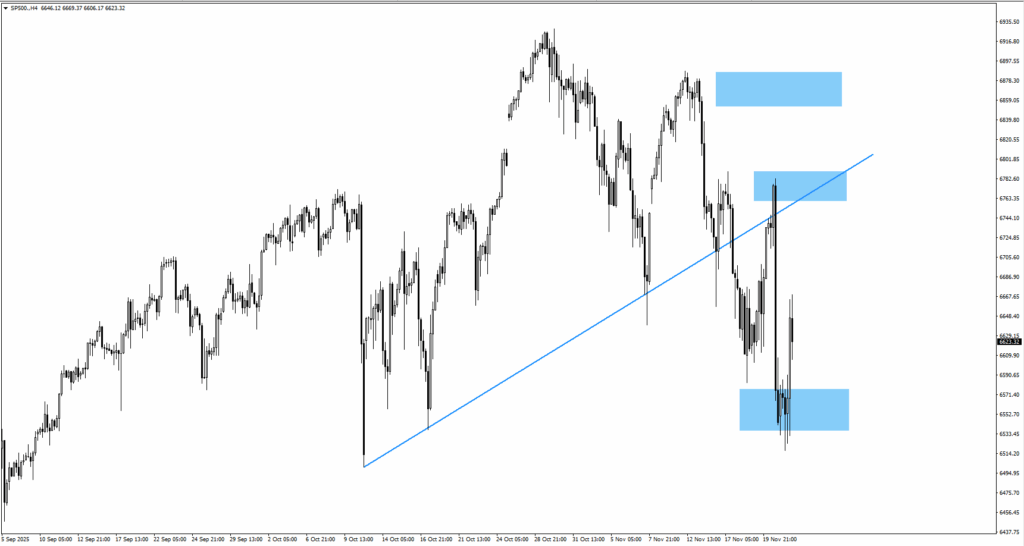
- Index rebounded as rate-cut optimism drove tech stocks higher.
- Traders watch 6,760 resistance for directional bias amid easing yields.
- Sustained buying above 6,700 could open the door to a year-end rally.
USD Index (USDX)
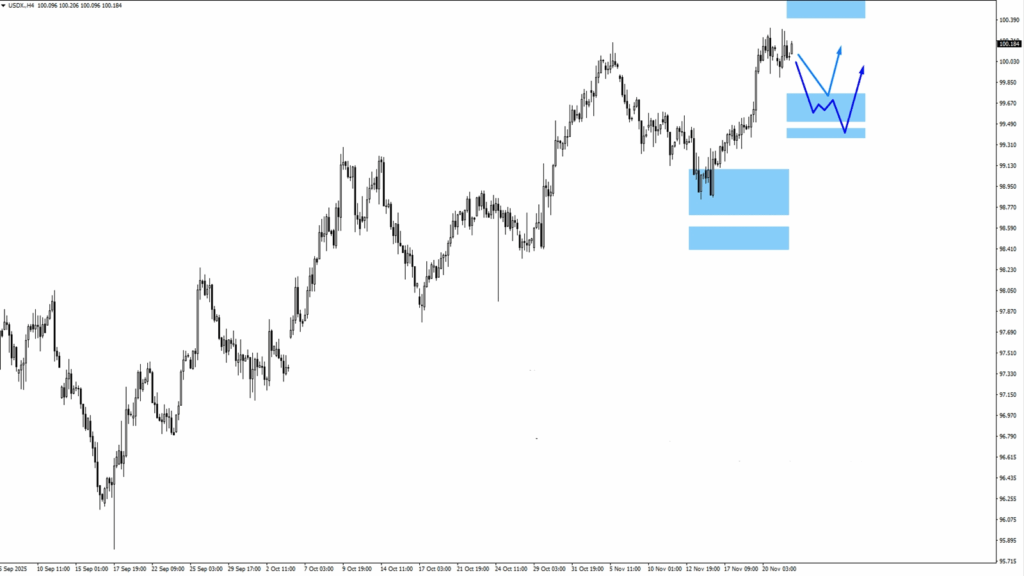
- USDX eased from its peak, testing the 99.65 zone for support.
- A bullish reversal could follow if the Fed tempers dovish expectations.
- Further downside to 99.45 remains possible if PCE cools sharply.
Bitcoin (BTCUSD)
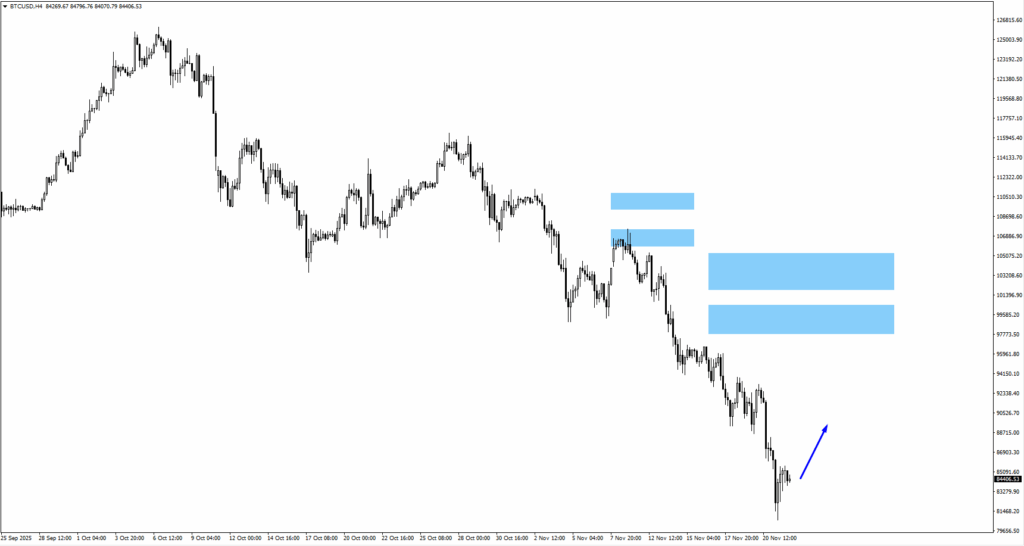
- BTC tested $81,700, slipping amid risk rotation.
- Consolidation patterns suggest potential continuation of short-term weakness.
- Traders eye support near $80,000, with resistance around $84,000.
US Oil (USOIL)
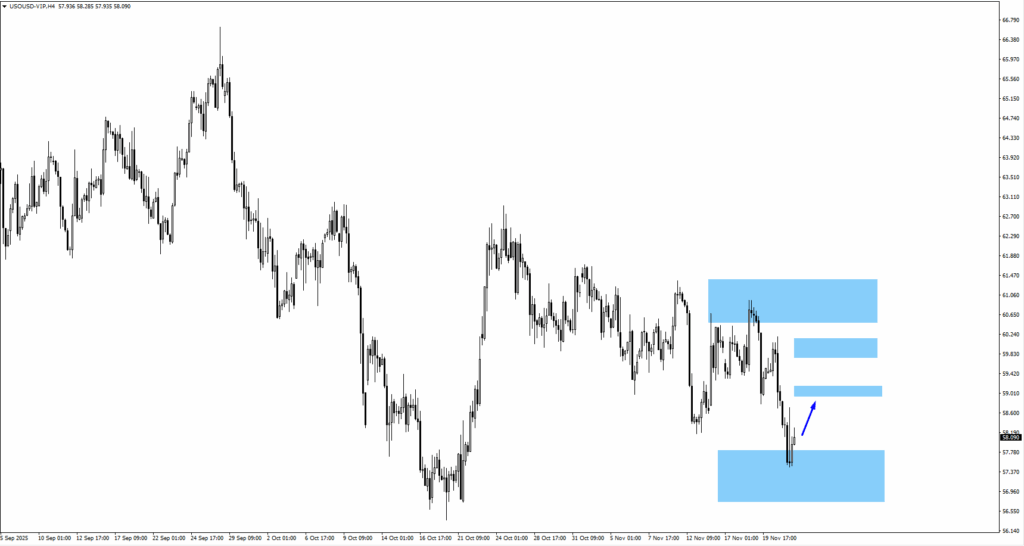
- Crude rebounded from $57.60 toward $59.80, aided by improving sentiment.
- Resistance sits at $61.05, with potential pullback zones near $59.05.
- Market focus shifts to OPEC+ signals and global demand data.
Bottom Line
The recent rally in global markets is being driven less by fresh data and more by a reset in the Federal Reserve’s tone. John Williams’ comments that policy is only “modestly restrictive” have opened the door to near-term easing, reigniting risk appetite across equities, gold, and crypto.
With the probability of a December rate cut climbing to 71%, traders have begun to reprice the path for monetary policy into early 2026.
For now, the data tells a mixed story. The US labour market continues to generate jobs, but the unemployment rate has drifted higher to 4.4%, and jobless claims have reached levels last seen in 2021. Inflation risks appear to be receding faster than growth, giving the Fed scope to move toward a more neutral stance.
A December rate cut would validate much of what markets have already priced in, but a hold accompanied by dovish language could still keep risk sentiment buoyant.







