





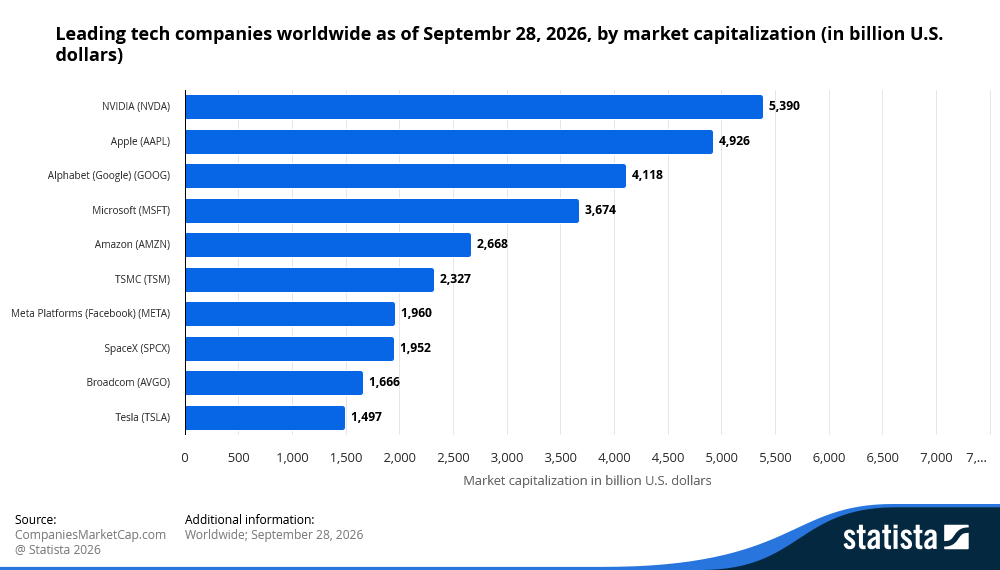
Anthropic is approaching the public market with a valuation normally reserved for the world’s largest technology companies. A reported IPO valuation above $2 trillion would place the AI company alongside Nvidia, Apple, and Microsoft, despite having only recently begun scaling its commercial business.
The potential mega-IPO arrives as investor appetite for artificial intelligence remains strong. Revenue is growing rapidly, demand for advanced AI models remains high, and Anthropic has positioned Claude as one of the leading systems in the race to commercialise AI.
But a Magnificent 7 valuation requires more than fast growth. It requires durable revenue, pricing power and profitable scale. Anthropic must prove that demand for AI can grow faster than the enormous computing costs required to serve it.
The AI premium has a very high price
Anthropic develops the Claude family of AI models and sells access mainly to businesses and developers. Unlike public companies, its valuation has previously been determined through private funding rounds. The IPO will give investors their first detailed look at financials, but the valuation depends heavily on which revenue measure is used.
| Measure | What it represents | Figure | Multiple at $2 trillion valuation |
| July 2026 run rate | Current monthly revenue annualised | Above $65 billion | About 31x |
| End-2026 run rate | Forecast monthly revenue annualised | Above $110 billion | About 17x |
| 2028 revenue | Reported full-year projection | $190–$200 billion | About 10x |
A run rate annualises the latest monthly revenue. It shows the current sales pace, but not necessarily what the company will earn over a full year.
The gap matters because the $2 trillion valuation depends less on today’s revenue and more on whether Anthropic can deliver the growth investors are pricing in for the years ahead. At a $2 trillion valuation, investors are paying for revenue they expect Anthropic to generate years from now. Against its current run rate, the valuation remains extremely demanding.
Why investors are keen
Anthropic’s strongest argument is the speed of its growth.
Revenue rose 12-fold in 2025 to almost $4.6 billion, while second-quarter 2026 revenue reached $11.5 billion. One quarter of this year generated more than double the company’s full-year revenue from 2025.
The company also argues that demand is currently exceeding available supply. According to the prospectus, growth is being limited mainly by access to computing power rather than a shortage of customers. That creates a different investment profile from companies still searching for demand. The challenge is not finding users, but building enough capacity to serve them.
Investor interest is also supported by scarcity. OpenAI has filed for an IPO but reportedly delayed its listing until 2027, leaving Anthropic as the only major pure-play AI model developer expected to reach public markets this year.
Nvidia is also reportedly considering a cornerstone investment of up to $10 billion, highlighting the strategic importance of Anthropic within the AI ecosystem.
The cost of scaling AI
The biggest pressure point is the gap between fixed infrastructure costs and flexible customer demand.
Anthropic has reportedly committed to at least $518 billion in computing capacity over roughly a decade across six infrastructure partners. Around 80% of those commitments are non-cancellable or payable regardless of usage. The company held around $20.28 billion in cash against those obligations.
Markets have seen similar infrastructure cycles before. Telecom companies built massive fibre networks in the late 1990s expecting internet demand to continue accelerating. The demand eventually arrived, but too slowly for many companies carrying heavy debt burdens.
Anthropic faces a different version of the same risk. The company does not own most of the infrastructure it is committing to. If demand slows, it remains responsible for the cost without owning the underlying assets.
Falling computing costs create another challenge. If newer chips make AI processing significantly cheaper, today’s long-term commitments could become expensive compared with future alternatives.
The competitive AI pricing power
Infrastructure is only one side of the equation. The other is whether customers continue paying premium prices for Anthropic’s models. Customer concentration adds to that uncertainty. Nearly a quarter of 2025 revenue came from two unnamed customers, while many large customers are not locked into long-term agreements.
Three forces could pressure pricing:
| Pressure point | Why it matters |
| Customer switching | Companies increasingly use systems that route tasks between different AI models based on cost and performance. |
| Open-weight models | Models from Meta, Alibaba, Moonshot AI and DeepSeek could limit pricing power for premium models. |
| Frontier competition | OpenAI, Google and xAI continue investing heavily in competing AI systems. |
The quality gap between closed and open models is narrowing. Stanford’s 2026 AI Index placed the leading closed model only slightly ahead of the leading open model as of March.
Pricing pressure is also emerging. OpenAI reduced API prices on new GPT-6 tiers, while Anthropic launched Claude Opus 5.5 at a lower cost per token than its previous version. The market opportunity is large, but competition may make it harder for any single AI company to maintain premium pricing.
Partners, profits and pressure points
Anthropic’s partnerships create both strength and complexity.
Amazon, Google and Microsoft are simultaneously investors, cloud providers, distributors and AI competitors. The structure gives Anthropic access to capital and infrastructure, but also creates overlapping incentives.
The company is highly dependent on these relationships. Around 47% of 2025 sales reportedly came through Amazon and Google’s cloud platforms.
Profitability remains another hurdle.
The reported $42 billion net loss includes around $34 billion related to financing instruments that could convert into shares. However, operating losses remain significant. On approximately $4.59 billion of 2025 revenue, Anthropic recorded an operating loss of around $8.06 billion.
Growth has been exceptional, but converting that growth into durable margins lies the challenge.
Assess the market pre-IPO
Anthropic does not need to prove that demand for AI exists. It needs to prove that demand can grow faster than its costs.
Three signals will shape investor expectations before the listing:
- Third-quarter results: whether revenue continues moving toward the year-end run-rate estimate.
- Final IPO pricing and float size: whether limited share availability creates early volatility.
- Customer commitments: whether major customers move toward longer-term agreements.
If growth continues, the revenue multiples could compress quickly and make the valuation easier to justify.
If growth slows, Anthropic could face hundreds of billions in infrastructure commitments without a similarly secure customer base.
Trade the Anthropic IPO theme with VT Markets
Anthropic is expected to list in November, but valuation discussions are already influencing AI market sentiment.
VT Markets offers a CFD on Anthropic, ANTHUSD, allowing traders to take a view on how the market values the company before its shares begin trading. IPO-related markets can experience sharp price movements, and CFDs involve leverage that can magnify both gains and losses.
Each company reflects a different part of the AI investment chain. Amazon and Google benefit from AI infrastructure demand while managing competitive overlap. Nvidia is tied more directly to AI hardware spending. Microsoft combines investment exposure with cloud and distribution relationships.
IPO developments often arrive outside US trading hours. VT Markets’ 24-hour share CFDs allow traders to respond to market-moving updates as they emerge.
Make an account today | Try a Demo | Download VT Markets APP
Tap for Trader’s Takeaway
Why is Anthropic’s IPO considered a mega-IPO?
A valuation above $2 trillion would place Anthropic among the world’s most valuable technology companies and make it one of the largest IPOs ever.
When is the Anthropic IPO expected?
Reports point to November, after the US midterm elections, though the final date and terms have not been set.
Can Anthropic justify a Magnificent 7-level valuation?
The company has strong AI demand and rapid revenue growth, but it must prove it can maintain pricing power, manage infrastructure costs and achieve profitable scale.
Can you get exposure to Anthropic before it lists?
Its shares cannot be bought before the IPO, but CFDs such as ANTHUSD on VT Markets let traders speculate on its price without owning shares. Listed partners such as Amazon, Alphabet, Nvidia and Microsoft offer indirect exposure, though those stocks respond to many factors beyond Anthropic.
How does Anthropic compare with SpaceX’s IPO?
At $2 trillion and up to $100 billion raised, it would exceed SpaceX on both valuation and deal size.
What are the biggest risks facing Anthropic after its IPO?
Major risks include high computing commitments, increasing competition from OpenAI and Google, pricing pressure from open-weight models, and customer concentration.
Start trading now — click here to create your real VT Markets account.



